Showing posts with label Strategy. Show all posts

Wednesday, July 1, 2026

Plateaus Are Visible Before They Are Felt

Plateaus Are Visible Before They Are Felt. Growth stalls announce themselves in leading indicators.

A business growth plateau forms long before revenue flattens. The revenue line aggregates decisions made in earlier quarters, so it reports a stall only after that stall has set. The earlier signals sit in pipeline composition, sales cycle length, customer mix and delivery capacity, and those measures move first.

Revenue Reports the Stall After It Has Happened

Revenue is a lagging aggregate. It sums the outcome of work that began weeks or quarters earlier, and it hides the composition of that work behind a single figure.

A company can hold revenue flat while its underlying position deteriorates. Existing customers expand, a large renewal lands, and the total looks stable while new acquisition has already stopped working.

The reverse happens just as often. Revenue dips for a reason unrelated to health, and the owner responds forcefully to a problem that does not exist.

Both errors come from the same source. A single aggregated number cannot distinguish between causes, and the causes are what any useful response has to address.

By the time the revenue line visibly bends, the decisions that produced the bend are old. The people responsible have moved on to other work, and the conditions that caused it may have shifted again.

That delay is the expensive part. Every month spent waiting for confirmation in the revenue line is a month during which the underlying cause compounds quietly.

The delay also distorts accountability. A stall attributed to the current quarter usually originated in decisions taken by people who are no longer responsible for the outcome, which makes the post-mortem unproductive.

The Indicators That Move First

Leading indicators share one property. They describe the inputs to revenue rather than revenue itself, and inputs change before outputs do.

The first is composition. A revenue figure held up by expansion inside existing accounts while new customer acquisition slows describes a business that has stopped growing and has not yet noticed.

The second is cycle length. Deals that take longer to close without any change in price or product suggest the offer no longer answers what buyers are asking as directly as before.

The third is exception volume. A rising share of deals that need a discount, a custom term or a special implementation indicates the standard offer no longer wins on its own merits.

The fourth is source mix. When referral and repeat business fall as a proportion of new pipeline, the market position that generated them has weakened even though the total may hold.

The fifth sits inside operations. Time from hire to full contribution, escalation volume and rework rates all rise before a delivery constraint appears as customer churn.

None of these require new systems to observe. Most businesses already hold the underlying data and simply do not arrange it in a way that makes direction visible.

Marketing efficiency belongs in the same set. Cost to acquire a customer rises before volume falls, because the easiest buyers are reached first and the remainder cost more to convince.

Retention behaviour is the quietest of the group. Renewal still happens, but the enthusiasm behind it fades, and support tickets or contract negotiations start to carry a different tone.

Why Owners Watch the Wrong Line

Reporting and detection are different jobs, and most management reporting is built only for the first. The distinction is rarely made explicit, so one system is asked to do both and does neither well.

A reporting dashboard answers what happened. It aggregates, it summarises, and it is designed to be read quickly by people who want a position rather than a diagnosis.

A detection layer answers what is changing. It tracks direction and rate rather than level, and it is deliberately noisy because early signals are weak by definition.

Owners default to reporting because reporting is what the accounting system already produces. The financial close arrives on a schedule, it carries authority, and it feels like the definitive account of the business.

It is definitive about the past. It is close to useless as a warning, because every figure in it describes work already delivered and cash already earned.

The habit is reinforced by comfort. A revenue figure that has not fallen permits the conclusion that nothing needs to change, and leading indicators withdraw that permission.

Detection also requires someone to own the interpretation. Numbers that move without an assigned reader produce no action, however early they arrived on the report.

There is a further reason the revenue line dominates attention. It is the number every stakeholder understands, so it becomes the language of every board meeting and every management conversation.

Leading indicators require explanation before they can be discussed. That cost is small, but it is enough to keep them off most agendas unless someone insists.

Stalls Follow Recognisable Patterns

Growth stalls are not idiosyncratic events. Companies arrive at them through a small number of routes, and each route leaves a distinct trace in the indicators before revenue moves.

One route is founder capacity. Every deal above a certain size still requires the owner personally, and the business grows only until the calendar of the owner is full.

Another is segment exhaustion. The original customer profile has been served thoroughly, and the next available customers are less similar, harder to win and more expensive to keep.

A third is offer plateau. What won the early market stops differentiating as competitors match it, and price pressure appears well before unit volume drops.

Knowing which route a business is travelling changes the response entirely. The recurring patterns that appear before a growing company stalls repay study, because the correct intervention differs sharply between them.

Founder capacity is addressed through delegation and hiring. Segment exhaustion is addressed through repositioning rather than through hiring more sellers, and applying either remedy to the other problem wastes the window.

A fourth route is channel dependence. Growth has come from a single source of demand, and the terms of that source change without warning or notice.

Each route also has a characteristic denial. Founder capacity is denied by claiming nobody else can handle the important accounts, and segment exhaustion is denied by blaming the market.

Building a Detection Layer That Fits the Business

A detection layer does not need to be elaborate. It needs to be specific to the constraint the business actually faces at that moment.

The first step is naming that constraint. A business limited by demand needs different early indicators than one limited by delivery capacity or by cash conversion.

Standard strategic exercises handle this badly. A conventional strengths and weaknesses review produces four lists and no ranking, which leaves the owner roughly where they started.

Tools that force a choice work better. Several structured alternatives to the standard strengths and weaknesses exercise exist to identify the binding constraint rather than to catalogue observations.

Once the constraint is named, the indicators follow from it. A demand constraint points at pipeline composition and cycle length. A capacity constraint points at utilisation, rework and escalation volume.

Review cadence matters as much as the choice of measures. Indicators reviewed once a quarter detect very little, because the window they exist to protect is shorter than the gap between reviews.

A monthly review with a named owner and a short written note is usually sufficient. The written note matters because it forces an interpretation rather than a glance at a chart.

Two or three indicators are enough to start. A longer list dilutes attention and produces a report that nobody reads carefully enough to notice a change.

Acting Inside the Window

Early detection is worth nothing without a willingness to act on incomplete evidence. That willingness is the part most owners have not built.

Leading indicators are ambiguous by construction. A lengthening sales cycle might reflect a market shift, a weaker pipeline, a new competitor or ordinary seasonality.

Waiting for the ambiguity to resolve defeats the purpose entirely. Certainty arrives at the same moment as the revenue impact, which is the outcome the indicator existed to prevent.

The practical response is proportionate investigation. A signal that moves in the same direction for two consecutive periods earns a specific question, not a restructuring.

Questions are cheap and fast. Ask which segment the lengthening cycle sits in, whether it affects new and existing buyers equally, and what changed in the period beforehand.

The investigation should have a deadline. An open question with no return date becomes a standing item that is discussed repeatedly and never resolved.

Most signals resolve into something small and fixable at that stage. The ones that do not are precisely the ones worth escalating long before they reach the revenue line.

The discipline is easier to sustain when the response is scaled to the signal. Owners who treat every early indicator as a crisis stop trusting the indicators within a few months.

A plateau is rarely a sudden event, whatever it feels like when the quarter closes. It is the visible endpoint of a slow change the business had ample opportunity to observe. The difference between a company that stalls and one that adjusts is seldom insight or resources. It is whether anyone was reading the measures that move first, and whether that reading was allowed to change anything.

Frequently Asked Questions

How do you tell a growth plateau from normal seasonality?
Seasonality repeats on a known schedule and affects the same measures each cycle. A plateau shows up as a change in composition rather than a change in level, which seasonality rarely produces. Comparing the same period across consecutive years separates the two quickly. If the mix of new and existing revenue has shifted, the cause is structural rather than seasonal.

Which single indicator gives the earliest warning?
No single indicator works across every business, because the earliest signal depends on the binding constraint. Demand-limited businesses usually see it first in sales cycle length or in the share of deals requiring an exception. Capacity-limited businesses see it first in rework, escalation volume and time from hire to contribution. Naming the constraint before choosing the measure avoids monitoring numbers that cannot move early.

Can a business grow revenue and be on a plateau at the same time?
Yes, and this is the most common version of the problem. Revenue can rise on expansion within existing accounts while the ability to win new customers has already degraded. The total conceals the deterioration until the existing base is fully expanded. Splitting revenue by source is the simplest way to see it.

How often should leading indicators be reviewed?
Monthly review suits most small and mid-market businesses. A quarterly cadence is usually too slow, because the advantage of a leading indicator is measured in weeks rather than quarters. Weekly review tends to amplify noise and produce reactions to nothing. The cadence should be short enough to preserve the window and long enough for a real trend to form.

What should happen when an indicator moves in the wrong direction?
The first response is a question, not a plan. A single period of movement is investigated rather than acted upon, and the investigation should be narrow and specific. If the same direction holds for a second period, the finding moves to whoever owns that part of the business. Escalating every wobble destroys confidence in the whole system.

Do smaller businesses need this kind of monitoring?
Smaller businesses need it more, because they have less financial cushion to absorb a late diagnosis. The system can be simple, often a single page reviewed monthly by the owner and one other person. Complexity is not what makes detection work. Consistency and a named reader are what make it work.

Wednesday, May 13, 2026

Assessment Only Helps If It Ends in a Decision

Description is not a decision. Most assessment output stops one step short of the thing that creates value.

A business maturity model describes where a company sits on a scale of operating discipline. That description earns its cost only when it forces a decision about what changes next. Most assessments produce an accurate picture, a tidy score, and no obligation to act on either one.

Description Is Not Diagnosis

Assessment is popular because it feels like progress without demanding commitment. A team spends several weeks gathering evidence, scoring dimensions, and producing a document everyone agrees is fair. Nothing in that sequence obliges a single person to behave differently on Monday morning.

The output is genuinely useful as a shared picture of the operation. Leadership teams frequently disagree about how mature the business really is, and a structured score ends that argument with evidence. Ending an internal argument is worth something, though it is not the same as choosing a path.

A maturity score describes a position on a scale and nothing beyond that. A diagnosis explains why the position exists and what specifically holds it in place. Most frameworks stop at the first and merely imply the second, leaving the reader to construct the causal story alone.

Understanding how staged maturity frameworks classify an operation clarifies what the instrument can and cannot deliver. Stages are comparative rather than prescriptive by construction. Knowing that a company sits at an early stage on process documentation says nothing about whether documentation is the constraint worth attacking this year.

Scores also carry a comfort that works against the reader. A number feels objective, and objectivity discourages the argument that would otherwise surface the real constraint. The most valuable moment in an assessment is usually the disagreement that a tidy score was designed to settle before anyone examined it.

The instrument itself shapes what ends up being found. Different tools examine different surfaces, and each surface produces a different list of problems. Reviewing how the common assessment instruments differ in what they surface before choosing one prevents an accidental narrowing of the question.

Tool choice made casually becomes an unexamined decision about what the company is permitted to notice. A survey of employee sentiment finds cultural problems every time it runs. A process audit finds process problems with equal reliability. Neither result is wrong, and neither result is complete.

Who gets asked matters as much as which instrument is used. Assessments run entirely through senior leadership describe the company as leadership believes it operates. Assessments that reach the people executing the work describe how it actually operates, and the two descriptions rarely match.

The Frameworks Stop One Step Short

The most widely used assessment format asks a team to list strengths, weaknesses, opportunities, and threats. It produces four columns quickly and gets a group talking, which explains its long persistence. It also contains no mechanism for turning any column into an action.

Four lists on a whiteboard describe a state of affairs and stop there. They do not rank items, weigh them against each other, or force any tradeoff. A team can complete the exercise honestly and leave the room with nothing at all decided.

The format feels productive because generating items is easy and agreeable. Nobody objects to naming a strength, and naming a weakness costs nothing when no budget follows from it. Difficulty appears only at the moment something must be funded at the expense of something else.

The exercise becomes valuable when a rule is attached to it in advance. Pushing a four-column review toward a specific operating change means agreeing beforehand which single weakness will be funded and which opportunity will be declined. The lists then serve the decision instead of quietly replacing it.

Facilitation quality decides whether the output reflects the company or the room. Unstructured sessions record the views of whoever speaks with the most confidence. Structured sessions collect input separately before discussion begins, which produces a very different set of items.

Sometimes the format itself is the binding constraint on the answer. Questions about sequencing, capital allocation, or competitive position do not fit into four boxes, and forcing them there flattens the answer beyond usefulness. Selecting from other structured frameworks suited to different questions is a matter of matching the shape of the tool to the shape of the problem.

Framework loyalty is a common and quiet form of failure. Teams reach for the instrument they already know rather than the one that fits, then treat its output as the complete picture. The instrument answered its own question faithfully and was simply asked the wrong one.

Assessment Earns Its Keep When It Names What Will Break

The version of assessment that justifies its cost is predictive rather than descriptive. It identifies what will fail next, under what conditions, and roughly when that failure arrives. That framing produces urgency, because a named future failure carries a date with it.

Companies that stall almost never stall suddenly or without warning. The conditions accumulate across quarters, visible to anyone examining the right indicators, and become obvious only once growth flattens. Recognizing the recurring patterns that precede a growth plateau converts assessment from a report card into an early warning system.

Those patterns tend to be structural rather than commercial in origin. Decision bottlenecks, undocumented knowledge, hiring ahead of process, and margin erosion hidden by revenue growth all appear well before the plateau does. None of them shows up anywhere in a sales forecast.

The decision bottleneck deserves particular attention because it hides behind good intentions. When every material choice routes through one or two people, the company runs at the speed of their available calendar. Growth increases the volume of decisions while leaving that calendar exactly as constrained as before.

Financial capacity deserves its own examination, entirely separate from operating maturity. A company can be operationally ready and financially unable to fund the next stage, and those two conditions demand completely different responses. Testing whether the balance sheet can actually fund the next stage keeps ambition tied to capacity.

Growth consumes cash before it produces any, which is the oldest lesson in the field and the most frequently relearned. Assessments ignoring working capital produce plans that read as sound and stall in the second quarter of execution. The operating plan and the cash plan have to be examined against each other.

The Decision Is the Deliverable

An assessment should end with a written decision rather than a written description. The document should name what the company will do next, what it will deliberately not do, who owns each choice, and what evidence would reverse it. Anything short of that is a briefing with a cover page.

That final element matters far more than its length suggests. Recording what would change the decision prevents the two most common outcomes: stubborn commitment to a plan that stopped working, and constant revision without any stated reason.

Ownership needs to be assigned to a person rather than a function. A decision owned by the leadership team is owned by nobody once the calendar fills again. A decision owned by a named individual with authority to act survives the return to ordinary work.

Deliberate omissions carry as much weight as commitments. A decision document that lists only what the company will pursue leaves every existing activity funded by default. Naming what stops, and when it stops, is what frees the capacity the new commitment requires.

Certain decisions should never be made inside a closed leadership team. Choices involving ownership structure, senior hiring, capital, or a change in market position carry consequences that internal consensus consistently underestimates. Recognizing the decisions that warrant an outside perspective before commitment is part of what mature assessment produces.

Cost is the objection arriving next, and it deserves a direct answer rather than a defensive one. Understanding what a structured strategic review actually costs allows the spend to be compared against the cost of the decision it informs. An assessment priced against a small decision is expensive, and the same assessment priced against a company-defining choice is trivial.

Timing follows the same logic that governs cost. Assessment run on a fixed calendar, with no pending decision attached, produces documents that circulate and settle. Assessment run immediately ahead of a funding round, a senior hire, or a market entry produces argument, which is the point.

Readiness questions about newer capability obey exactly the same rule. Evaluating whether the organization is prepared to adopt automation at all is worth doing only if the result determines whether adoption proceeds this year. A readiness score that changes no behavior is a document rather than a decision.

The test for any assessment is short and unforgiving. Ask what the company will do differently because the work was done, and ask who is accountable for doing it. If the honest answer is that leadership now understands the situation better, the exercise produced understanding and nothing further. Understanding is cheap to acquire and easy to mistake for progress, and the difference between the two is a decision somebody was willing to sign.

Frequently Asked Questions

What is a business maturity model used for?
It places an operation on a staged scale so leadership can agree on where the company currently stands. The value lies in ending internal disagreement about the starting position. On its own, the model does not indicate which weakness should be addressed first. That judgment requires a separate step the framework does not supply.

Is a four-column strengths and weaknesses review still worth doing?
It remains useful for surfacing views quickly across a group of people. The weakness is that it produces lists without ranking or tradeoffs attached. Attaching a rule beforehand, such as committing to fund one weakness and decline one opportunity, converts it into a decision tool. Without that rule, the exercise usually ends roughly where it started.

How often should a company run a formal assessment?
Frequency matters considerably less than trigger. A sound trigger is a pending decision of real consequence, such as a funding round, a senior hire, a market entry, or a stall in growth. Running an assessment on a fixed calendar with no decision attached tends to produce documents nobody acts on. The decision should pull the assessment forward rather than the reverse.

What separates a useful assessment from a report nobody reads?
A useful assessment ends in a written choice with a named owner and a reversal condition. It states what the company will stop doing as clearly as what it will start. Reports describing only the current state give leadership nothing to act against. The presence or absence of a named decision is the entire difference.

Should assessment cover financial capacity as well as operations?
Yes, because the two surfaces produce different constraints and different remedies. A company can have disciplined processes and still lack the working capital to fund its next stage. Growth consumes cash ahead of producing it, so plans built on operating readiness alone tend to stall partway through execution. Both surfaces need examining before any plan gets approved.

Can a leadership team assess itself?
Partly, and the limits are predictable enough to plan around. Internal teams see process and workflow accurately and consistently underestimate the risk attached to decisions they have already committed to emotionally. Choices about ownership, capital, senior hiring, and market position benefit from an outside reader. The value of that outsider is disagreement rather than expertise.

Thursday, April 9, 2026

You Cannot Analyse Your Way Out of a Cash Constraint

You Cannot Analyse Your Way Out of a Cash Constraint. Frameworks describe position.

Financial readiness is the question of whether a business can fund a growth decision from the cash it will actually hold, at the time it will actually need it. Frameworks describe where a company stands. Cash decides what that position permits the company to do this quarter, and no amount of analysis converts one into the other.

Position Is Not Permission

A strategic analysis can be entirely correct and completely unusable. It can identify the right market, the right product change, and the right sequence of moves. None of that matters if the company cannot fund the first step without missing payroll.

Owners rarely make this mistake deliberately. They make it because the two questions are answered by different people at different times. Strategy is discussed in a planning session and cash is discussed with the bookkeeper.

The two conversations never meet, and so a plan gets approved on its merits rather than on its affordability. The constraint only surfaces later, usually as a surprise, usually at the worst possible moment.

The corrective is procedural rather than analytical. Every strategic option should be presented alongside the cash it consumes before it returns anything. If that figure is not on the page, the option has not been fully described.

What Financial Readiness Actually Measures

Financial readiness is not the same as profitability, and confusing the two causes real damage. A profitable business can be entirely unable to fund growth, and an unprofitable one can occasionally afford a bet if it holds enough cash.

Readiness measures three things. It measures how much cash the business holds and can access. It measures how quickly cash converts through the operating cycle. It measures how much of the coming period is already committed to obligations that cannot be moved.

The third item is the one most often skipped. Committed cash is not available cash, even though it sits in the same account. Tax liabilities, loan repayments, seasonal supplier payments, and payroll for staff already hired all reduce the genuinely discretionary balance.

A business that measures readiness against the bank balance rather than the uncommitted balance will overestimate its capacity every time. The gap between those two figures is where most funding surprises live.

Working through whether the business can genuinely afford the growth it is planning means running that calculation before the strategy is chosen rather than after. The order matters more than the sophistication of the method.

Why Frameworks Feel Like Progress

Analytical frameworks are popular because they are satisfying. They convert an anxious, formless worry into a structured page with quadrants and headings. That conversion feels like the problem has been handled.

It has not been handled. It has been described. Description is a real contribution and it is routinely mistaken for a decision.

The mistake is easy to spot after the fact. A leadership team completes a thorough analysis, agrees it was valuable, and then makes exactly the same operating choices it would have made anyway. The analysis changed the vocabulary and not the behaviour.

None of this makes frameworks worthless. A structured analysis that actually changes what a small business decides is a different exercise from one that produces a filled-in template. The difference is whether the output feeds a specific choice with a deadline.

The test is straightforward. Before starting any analysis, name the decision it will inform and the date that decision must be made. An analysis with no decision attached is an interesting document and nothing more.

Growth Consumes Cash Before It Produces It

This is the mechanism that catches most small and mid-market businesses, and it catches them precisely because they are succeeding. Growth is not free. It is funded in advance and repaid later.

A larger order requires more inventory, bought before the invoice is raised. A bigger team requires salaries paid before the additional output reaches a customer. A new location requires deposits, fit-out, and staffing months before it trades at capacity.

Each of these creates a gap between money leaving and money returning. The faster the growth, the wider the gap. A business growing quickly can be more fragile than the same business growing slowly, even though every other indicator looks better.

Owners often read the warning signs backwards. Sales are rising, the pipeline is full, the team is busy, and the bank balance is falling. The natural interpretation is that the balance will recover once the current work invoices out.

Sometimes it does. Often the next tranche of growth consumes the recovery before it arrives, and the business enters a pattern where every good quarter tightens the position further. Escaping that pattern requires a deliberate decision to slow down, which almost nobody makes voluntarily.

There is a second reason growth tightens the position. Larger customers pay more slowly than small ones, and winning them is treated as an unambiguous success. The revenue improves and the collection period lengthens at the same time.

Neither effect is visible on a profit statement. Both are visible immediately on a cash forecast, which is why the forecast is the instrument that matters during expansion.

The Questions That Come Before the Analysis

Four questions establish whether a strategic conversation can proceed usefully. They take an afternoon rather than a project, and they should be answered before any framework is opened.

The first asks how many weeks the business could operate if revenue stopped entirely tomorrow. Not months, weeks, and calculated against committed outgoings rather than average ones. That figure sets the boundary on how much risk is available.

The second asks how long it takes for a unit of spend to return as revenue. That is the operating cycle, and it determines how much funding any growth step requires before it becomes self-sustaining.

The third asks what proportion of the coming quarter is already spoken for. Committed costs, scheduled repayments, and known liabilities all reduce the room to manoeuvre in ways that do not appear on a profit statement.

The fourth asks what access to additional funding exists, on what terms, and how quickly it can be drawn. A facility that takes ten weeks to arrange is not available for a decision that must be made this month.

A business that can answer those four questions has a real constraint to plan against. A business that cannot is guessing, and every subsequent analysis inherits that guess as an assumption.

Where Analysis Earns Its Place

None of this argues against analysis. It argues for a specific ordering, in which the cash position is established first and the analysis is conducted inside that boundary.

Analysis conducted within a known constraint is more useful, not less. Options that cannot be funded are removed early, which shortens the process and sharpens the debate about what remains. Teams that plan without a constraint spend most of their energy on options they were never going to take.

The constraint also changes the character of the recommendations. Faced with limited cash, teams stop proposing transformation and start proposing sequence. Sequence is almost always the better answer for a business of this size.

Sequenced growth funds each step from the returns of the last. It is slower than the plan the analysis would have produced without the constraint, and it survives contact with a bad quarter. That trade is worth making explicitly rather than discovering by accident.

The strongest planning conversations tend to be the least ambitious on paper. They pick one move, fund it properly, define what success looks like, and specify what happens if the return arrives late. That last element is what separates a plan from a hope.

A rolling cash forecast is the practical instrument. It projects receipts and payments week by week for the next several months and is updated weekly rather than monthly.

Weekly updating matters because the errors compound. A forecast reviewed monthly gives the business a handful of chances a year to notice a developing problem. A weekly one gives it enough warning to act while options still exist.

Accuracy in the near weeks matters more than precision in the distant ones. The next month should be close to exact, because most of it is already committed and knowable. Beyond that, directional accuracy is sufficient for the decisions the forecast supports.

The forecast does not need to be sophisticated. A spreadsheet maintained honestly beats an elegant model maintained occasionally. What it needs is to be believed, which means the person maintaining it must be free to report bad news without consequence.

That last condition fails more often than the arithmetic does. Where a forecast is used to assign blame, it stops being accurate quickly, and the business loses the one instrument that gives it advance warning.

Strategy work is valuable and cash work is unglamorous, which is why the second is chronically underdone in businesses that pride themselves on thinking clearly. A company that knows its constraint can plan aggressively inside it. A company that does not know its constraint will eventually be told what it was, at a moment chosen by the constraint rather than by the owner.

Frequently Asked Questions

What is the difference between financial readiness and profitability?
Profitability describes whether revenue exceeded cost over a completed period. Readiness describes whether cash will be available at the moment a commitment falls due. A profitable business with slow collections and fast payments can run out of cash while its accounts look healthy. The two measures answer different questions and neither substitutes for the other.

How far ahead should a cash forecast run?
Most small and mid-market businesses are well served by a rolling forecast covering the next three to six months, updated weekly. Shorter horizons miss seasonal effects and scheduled liabilities. Longer horizons carry so much assumption that the later weeks stop being informative. The discipline of updating matters more than the length of the window.

Does this mean strategic frameworks are a waste of time?
No. Frameworks organise thinking and surface factors that would otherwise be missed. The failure is using them as a substitute for a decision rather than an input to one. Any analysis should be attached to a named choice with a deadline before the work begins.

What if the numbers say growth is not affordable?
That is a usable answer rather than a failure. The response is usually to sequence the growth into smaller funded steps rather than abandon it. Smaller steps also generate evidence about whether the underlying assumptions hold. Businesses that discover the constraint early keep more options than those that discover it mid-commitment.

Who should own the cash forecast in a smaller business?
Ownership belongs to whoever has visibility of both commitments and collections, often a finance lead or an operations manager. The owner of the business should read it weekly regardless of who maintains it. Delegating the maintenance is sensible. Delegating the attention is not.

How does external funding change the picture?
Available funding widens the constraint but does not remove it, because borrowed cash carries a repayment schedule that becomes a future commitment. Facilities also take time to arrange, which means they are only useful if secured before they are needed. Arranging access while the position is strong is far easier than arranging it under pressure. The terms available reflect the position at the moment of asking.

Wednesday, April 1, 2026

Some Decisions Are Too Expensive to Make Alone

Some Decisions Are Too Expensive to Make Alone. The cost of an outside opinion is knowable in advance.

A business assessment is a structured outside review of how a company earns, where it loses, and which constraints cap the next stage of growth. The price is quoted before any work begins. The cost of a major decision made in isolation is discovered afterwards, and it never arrives as a line item with a name attached.

The Comparison Is Usually Framed Backwards

Owners weigh the price of an assessment against the price of doing nothing. Doing nothing appears free. It is not free, but its cost shows up late and gets attributed to something else.

The honest comparison sets a known price against an unknown one. On one side sits a fee that can be stated in advance. On the other sits a spread of outcomes from a decision that no outside party has examined.

Those two things are not equivalent in the way a budget line makes them look. One is a purchase. The other is exposure. Treating them as the same kind of commitment is what sends the whole conversation sideways.

The useful question is not whether the assessment is expensive. The question is whether the decision it informs is expensive enough to justify a second set of eyes. Most owners answer by looking at the wrong side of the ledger.

What an Assessment Actually Buys

An assessment does not buy an opinion. It buys a documented view of the operating reality, assembled by someone with no stake in the internal story. That distinction matters more than the analysis attached to it.

Every company runs on a set of shared explanations. Sales slowed because the market softened. Margin slipped because a supplier raised prices. Delivery ran late because the team was short-handed.

Some of those explanations are accurate. Most are partly accurate and have gone unchallenged long enough to feel settled. An outside review tests them against the record rather than against memory.

What the buyer receives is a smaller set of decisions, each better defined. Ambiguity is expensive because it multiplies the plausible next moves. Narrowing the field is the actual product, and the written analysis is only its packaging.

There is a further benefit that rarely appears in a proposal. An assessment forces the leadership team to state, out loud and in front of a stranger, what the business is trying to become. Many teams discover during that conversation that they disagree.

The Decisions That Do Not Survive Isolation

Not every choice needs outside input. Most operational calls should be made quickly by the person closest to the work. The category that breaks under solitary judgment is narrow and identifiable.

Three conditions define it. The decision is hard to reverse. It commits cash across more than one quarter. Nobody in the room has watched the same decision fail before.

Any two of those conditions appearing together should slow the process down. All three together should stop it until an outside view has been taken. The conditions are not exotic, and most owners can identify them without help.

Hiring a senior leader qualifies. So does entering a new market, taking on debt to fund expansion, replacing a core system, or restructuring how the company charges for its work. Each of these is a bet that will not reveal its result for months.

The pattern behind them is consistent. The owner has strong instincts built from experience, and those instincts were built inside a version of the business that no longer exists. Instinct scales badly across a structural change.

A closer look at the specific choices growing companies should never make in isolation shows how stable that list is across industries. The categories change name from sector to sector. The underlying risk does not.

Why Internal Review Rarely Substitutes

The obvious objection is that a company already has advisers. There is an accountant, a lawyer, a board, or at minimum a leadership team that meets weekly. All of that is real, and none of it does this particular job.

An accountant reviews what happened. A lawyer reviews what is permitted. Neither is asked to judge whether the operating model still fits the market, and neither is paid to volunteer that view.

The leadership team faces a different problem. Its members are evaluating a decision that will change their own scope, budget, and reporting line. Honest analysis from people with skin in the outcome is possible, but it is not the default and it should not be assumed.

The board, where one exists, sees a curated version of the business. Board packs are prepared by the same people whose judgment is under review. That is not dishonesty. It is the natural compression that happens when a complicated quarter is summarised for an hour of discussion.

There is also the question of who is allowed to ask. Junior people frequently see the operational truth first, because they handle the exceptions the system was never designed for. Very few of them will raise it with an owner unprompted.

An outside reviewer can ask those people directly and treat the answers as evidence rather than as complaint. That access is often the single most valuable part of the engagement. It is also the part that internal process almost never replicates.

Outside review works precisely because the reviewer has no future in the org chart. The absence of a stake is the qualification. Anyone who will still be in the building next year has a reason, however small, to shade the account.

The Price Is Knowable, Which Is the Whole Point

Buyers hesitate on assessments because the scope feels open-ended. That hesitation is reasonable when the scope genuinely is open-ended, which signals a badly designed engagement rather than a badly chosen buyer.

A well-defined assessment states what will be examined, who will be interviewed, which documents are required, and what the deliverable contains. It ends on a stated date. The fee does not move unless the scope moves, and scope changes are agreed in writing before work continues.

Anyone weighing the investment should understand how assessment pricing is actually constructed before assuming the range is arbitrary. Fees track the depth of the review and the size of the operation. They do not track the size of the problem the review might uncover.

Compare that with the alternative. A wrong senior hire costs the salary, the recruitment fee, and months of reduced output. It also costs the departure of good people who reported to that leader.

Then comes the delay to whatever the hire was supposed to deliver, which is usually the reason the role existed. None of that is quotable in advance. It is only ever counted afterwards, and usually not counted at all.

The asymmetry is the argument. One path has a ceiling. The other has a long tail, and the tail is where the damage lives.

A useful assessment feels uncomfortable in the middle and clarifying at the end. If it feels pleasant throughout, the reviewer has been managed rather than engaged.

The early interviews should surface disagreements the leadership team has been routing around. The middle should produce at least one finding the owner did not want. The end should reduce the decision to a small number of options with the consequences of each stated plainly.

Recommendations should be specific enough to argue with. A recommendation nobody can disagree with is not a recommendation. It is a description of the current state with encouraging adjectives added.

The deliverable should also be honest about what remains unknown. Some questions cannot be settled from outside, and a reviewer who claims otherwise is selling confidence rather than analysis. Naming the residual uncertainty is part of the value.

When Skipping It Is the Right Call

Outside review is not always warranted, and pretending otherwise would be dishonest. A reversible decision made with money the business can afford to lose does not need a formal process. Speed has real value, and consuming weeks to validate a small bet destroys it.

Skipping is also correct when the owner has made the same decision before, in the same business, at roughly the same size, and remembers what went wrong. Earned pattern recognition is genuine expertise. It is simply narrower than most owners believe.

The mistake is applying that logic to the wrong category. A decision that feels familiar is not the same as a decision that is familiar. Familiarity is a feeling produced by confidence, and confidence rises fastest in people with the least recent exposure to being wrong.

The test is simple enough to run in a meeting. Ask what would have to be true for this to fail, then ask who in the room is positioned to notice that first. If the answer to the second question is nobody, the decision is being made alone regardless of how many people are sitting at the table.

Companies rarely fail from a single catastrophic choice. They accumulate a run of medium decisions made confidently, in isolation, each defensible on its own, which together commit the business to a shape nobody chose deliberately. Outside review interrupts that accumulation. The interruption, not the report, is what the money actually buys.

Frequently Asked Questions

What does a business assessment actually include?
A defined assessment covers financial performance, operating process, organisational structure, market position, and the constraints linking them. The reviewer examines documents, interviews the leadership team and often people below it, and compares stated intentions against recorded results. The deliverable is a written analysis with prioritised findings and specific recommendations. Scope should be agreed before work begins so the buyer knows what is and is not covered.

How do you know whether a decision is big enough to warrant one?
Three tests apply. Ask whether the decision can be reversed cheaply, whether it commits cash beyond the current quarter, and whether anyone involved has made the same call before and watched it fail. A decision meeting two of those tests deserves outside input. A decision meeting all three should not proceed without it.

Is an assessment worth it for a smaller company?
Smaller companies often benefit more, because they make fewer large decisions and each one carries proportionally greater weight. A larger organisation can absorb a bad call inside a portfolio of other activity. A small business frequently cannot. Scope should be sized to the operation, which keeps the fee proportionate to the risk being managed.

Can an internal team run the assessment instead?
Internal teams can gather the data competently and should. What they cannot reliably do is judge the findings without regard to their own position. Every internal reviewer has a stake in which department turns out to be the problem. That does not make internal work worthless, but it does mean the conclusions need external testing.

How long should the process take?
Most assessments of a small or mid-market business run several weeks rather than several months. Longer engagements usually indicate scope that was never properly bounded. The deliverable should land while the decision it informs is still open. An analysis that arrives after the choice has been made is an expensive history lesson.

What happens if the findings are ignored?
That outcome is common and worth planning for. Recommendations fail to land when they require a change the owner was never willing to consider, which is why the willingness question belongs at the start rather than the end. A capable reviewer establishes early what is genuinely open for change. Findings outside that boundary should still be stated, but nobody should be surprised when they sit unactioned.

Tuesday, March 24, 2026

Practices Are Not Selling Because They Are Failing. They Are Selling for Negotiating Power

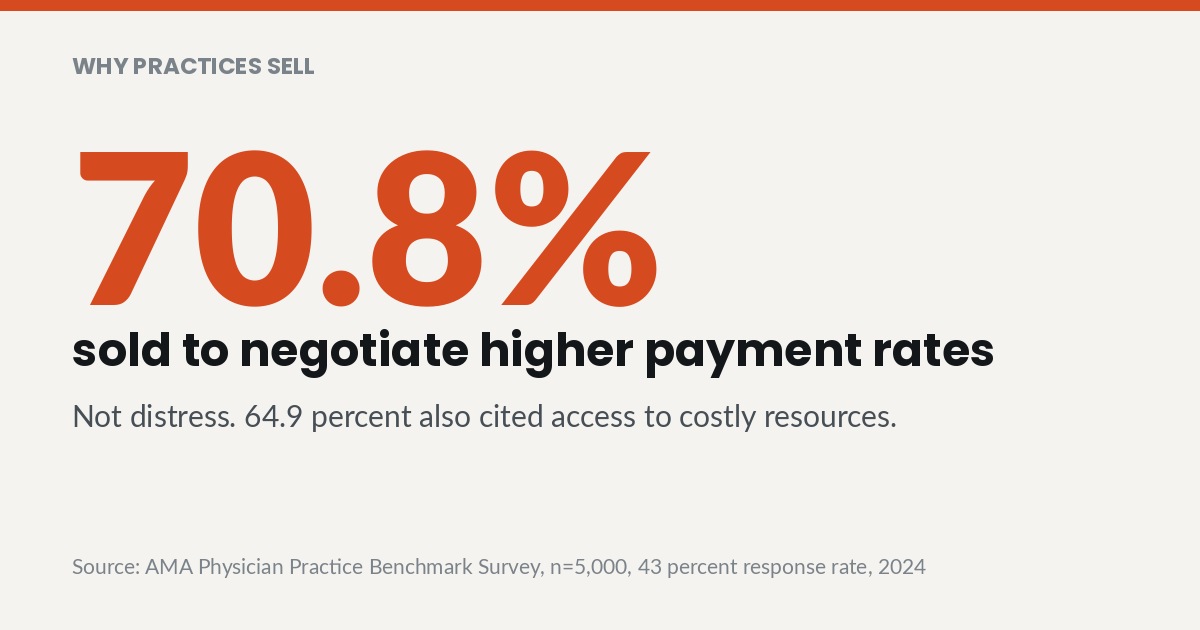
70.8% sold to negotiate higher payment rates. AMA Physician Practice Benchmark Survey, n=5,000, 43 percent response rate, 2024

Physician practice management is the operating discipline of running a medical practice as a business: payer contracting, revenue cycle, staffing and compliance. The reason it matters now is what sellers actually say. The AMA found that 70.8 percent of practices that sold cited the ability to negotiate higher payment rates. That is a contracting problem, not a distress signal.

The stated reasons for selling are not distress reasons

The standard account of practice consolidation describes exhausted physicians and failing economics. Sellers describe something more specific. The AMA Physician Practice Benchmark Survey for 2024, drawn from 5,000 physicians at a 43 percent response rate, asked practices that sold why they did it.

The top answer was payment rates. Seventy point eight percent cited the ability to negotiate higher payment rates as a reason for the sale. The next two answers were access to costly resources at 64.9 percent and managing payer regulatory and administrative requirements at 63.6 percent.

Read those three together and a picture forms that has nothing to do with a practice running out of patients. All three describe a relationship with payers rather than a relationship with patients. Practices are not exiting a broken market. They are exiting a weak negotiating position.

That distinction changes the entire diagnostic. A failing practice has an operations problem, a demand problem or a cost problem, and each has known remedies. A practice that sells for rate improvement has none of those. It has a bargaining problem, and bargaining power comes from structure.

What negotiating position is actually made of

Payer contracting rewards a short list of attributes and practice quality is not first among them. Network adequacy sits at the top. A payer that cannot build an adequate network in a geography without a particular group will pay that group differently.

Patient volume and geographic coverage follow. A group representing a meaningful share of a specialty in a market has a credible alternative to accepting terms. A practice representing a small fraction does not, regardless of outcomes or patient satisfaction.

Data comes third and is the most neglected. Practices that can demonstrate cost per episode, referral patterns, quality measures and utilization performance can argue from evidence. Most independent practices cannot produce those figures, which reduces negotiation to accepting a fee schedule as presented.

Nothing on that list correlates with clinical excellence at the individual practice level. That is the uncomfortable part of the finding. Physicians are being asked to solve a structural problem with professional merit, and merit is not the currency being priced.

The practical consequence shows up every renewal cycle. A practice requests an increase, receives a standard response, and concludes the payer is unreasonable. The payer is behaving rationally toward a counterparty with no alternative to offer.

Fragmentation is the underlying condition

The scale picture explains why so few practices hold a strong position. US Census County Business Patterns for 2023 counts 204,617 offices of physicians establishments averaging 13.2 employees, with 52.7 percent having fewer than five.

The AMA data agrees from a different angle. Physicians in practices of ten or fewer fell to 47.4 percent in 2024, below half for the first time, and 49.2 percent of private-practice physicians work in practices of fewer than five physicians.

An industry composed largely of very small units facing a small number of very large payers has a predictable outcome. The counterparty with concentration sets terms. The counterparty with fragmentation accepts them and calls the result market rates.

Consolidation is the market solving that imbalance in the crudest available way. Practices merge into entities large enough to be negotiated with rather than dictated to. Every seller in that 70.8 percent figure is buying a seat at a table they could not otherwise reach.

The destination is employment, not partnership

The transaction is frequently described as joining a larger group. The aggregate data describes something more definitive. Physicians in wholly physician-owned practices fell to 42.2 percent in 2024 from 60.1 percent in 2012, per the AMA.

Hospital-owned practice participation rose to 34.5 percent from 23.4 percent over the same period. Physicians employed directly by a hospital rose to 12.2 percent from 5.6 percent in 2012.

The employment share tells the plainest version. The AMA reports 57.5 percent of physicians are employees and 7.1 percent are independent contractors as of 2024. A majority of American physicians now work for someone else.

Rate improvement obtained through acquisition arrives bundled with governance changes that no contract negotiation would have produced. Scheduling, staffing ratios, referral direction and technology decisions transfer with the ownership stake. Physicians who sold for a payer contracting reason acquired a much broader set of consequences.

None of that makes the decision wrong. It makes the accounting incomplete. A rate increase quantified in advance sits against governance costs that surface gradually and are rarely modeled during diligence.

The open question about scale and independence

The honest position is that scale genuinely works for rate negotiation, and no operating improvement fully substitutes for it. Pretending otherwise sets independent practices up for disappointment. The productive question is how much bargaining power is reachable without an equity sale.

Structures that aggregate without acquiring

Independent practice associations exist precisely to negotiate on behalf of practices that remain separately owned. Clinically integrated networks go further, permitting joint contracting where practices demonstrate genuine clinical integration. Both structures carry real legal requirements and neither works as a paper arrangement.

Management services organizations formed by independents deliver the administrative scale without the ownership transfer. Billing, credentialing, human resources, purchasing and technology run once for many practices. That directly addresses the 64.9 percent who cited access to costly resources and the 63.6 percent who cited administrative and regulatory burden.

Value-based contracting offers a different route. A practice that can document total cost of care performance negotiates on outcomes rather than on volume. Payers pay differently for demonstrated savings, and that argument does not require size in the same way a fee schedule negotiation does.

What each route demands first

Every one of these paths requires data the practice does not currently produce. Joining an independent practice association without cost and quality reporting means joining as a passenger. Entering a value-based arrangement without knowing current performance means accepting risk blindly.

Building that reporting capability is an operations project, not a clinical one. It requires someone to define the measures, integrate the sources and hold the reporting cadence. Practices without a full-time operations executive frequently engage fractional COO leadership to build the function before any contracting conversation begins.

The controllable half of the reimbursement problem

While rate negotiation depends on structure, realized revenue depends on execution, and the second half is entirely controllable. Contracted rates only matter to the extent claims are actually paid at them.

Denial behavior varies more than most practices assume. KFF analysis of CMS federal transparency data for 2024 found in-network claim denial rates in marketplace plans averaging 19 percent, with insurer-level variation from 13 to 35 percent.

A practice with strong contracted rates and weak denial management collects less than a practice with modest rates and disciplined revenue cycle operations. Eligibility verification, documentation standards, clean claim rate and appeal discipline determine which of those two a practice becomes.

Denial rate by payer is also negotiating evidence. A practice arriving at renewal able to demonstrate that one insurer denies far above the others has changed the conversation from a rate request into a performance discussion. Most practices arrive with neither the data nor the framing.

Group purchasing works the same way on the cost side. Supplies, malpractice coverage, technology contracts and staffing services are all priced against volume that independents can aggregate without merging. The savings are smaller than a rate increase and considerably easier to obtain.

Reframing the decision

Practices considering a sale usually evaluate the offer against the status quo. That comparison is incomplete because the status quo already assumes the practice will not change how it operates or contracts.

The fuller comparison includes a third option. Build the reporting, join or form an aggregating structure, fix the revenue cycle, then evaluate offers from a stronger position. A practice that does this either negotiates better independently or sells at better terms, and both outcomes beat the current path.

Time is the real constraint. Aggregating structures take years to establish and value-based track records take years to accumulate. Practices that begin the work while an offer is on the table have already lost the option they are trying to preserve.

Administrative burden deserves the same treatment. It is genuinely heavy, and it is also the component most improved by process design rather than by ownership change. Practices that fix it internally remove one of the three reasons sellers gave.

The most cited reason practices sell is a negotiating problem wearing the costume of an economic one. That is worth sitting with, because negotiating problems have structural answers and economic problems do not always. The question independent medicine has not seriously answered is whether physicians are willing to build the shared infrastructure that would make independence viable, or whether selling remains simply easier than organizing.

Frequently Asked Questions

Why do practices sell if they are financially stable?
The survey evidence points to contracting position rather than financial distress. The AMA found for 2024 that 70.8 percent of practices that sold cited the ability to negotiate higher payment rates as a reason, followed by 64.9 percent citing access to costly resources and 63.6 percent citing payer regulatory and administrative requirements. None of those three describes failing demand or unsustainable cost. Stable practices sell because the ceiling on independent negotiating position is structural rather than operational.

Can a small practice improve its reimbursement rates without merging?
Improvement is possible but bounded, and the bounds should be stated honestly. Independent practice associations, clinically integrated networks and value-based contracting arrangements allow practices to negotiate with more standing while remaining separately owned. Each requires cost, quality and utilization data that most practices do not currently produce. Building that reporting capability is the prerequisite step, and it takes considerably longer than practices expect.

How much does practice size actually matter to payers?
Size affects network adequacy, which is what payers price. US Census County Business Patterns for 2023 counts 204,617 offices of physicians establishments averaging 13.2 employees, with 52.7 percent having fewer than five. A single practice at that scale rarely represents enough of a specialty in a market to alter a payer's network. Groups large enough to create an adequacy gap negotiate on different terms.

What should my practice fix before entering a payer negotiation?
Reporting comes first because negotiation without evidence is a request rather than a discussion. A practice should be able to produce denial rate and appeal outcomes by payer, cost per episode, referral patterns and quality measures. KFF analysis of CMS data for 2024 showed marketplace in-network denial rates averaging 19 percent with insurer-level variation from 13 to 35 percent, which means payer-specific performance is a real and arguable point. Practices that cannot document their own numbers negotiate against a fee schedule they have no basis to contest.

Is hospital employment different from private equity acquisition for physicians?
The governance outcome is similar even where the structures differ. AMA data for 2024 shows physicians in hospital-owned practices rising to 34.5 percent from 23.4 percent in 2012, and physicians employed directly by a hospital rising to 12.2 percent from 5.6 percent. In both models, decisions about scheduling, staffing and referrals move away from the practicing physician. Physicians evaluating either option should examine the specific governance terms rather than the ownership label.

How long does it take to build an alternative to selling?
Realistically it takes years rather than months. Clinically integrated networks require demonstrated clinical integration, value-based contracts require a performance track record, and management services arrangements require practices willing to standardize their operations. Revenue cycle improvements deliver faster and can begin immediately, which makes them the sensible starting point. Practices that begin only after receiving an acquisition offer have already run out of the time the alternative requires.

Tuesday, February 10, 2026

Midsize Firms Grew Profit Per Lawyer 25.5 Percent Since 2019. The Am Law 100 Grew 53.7

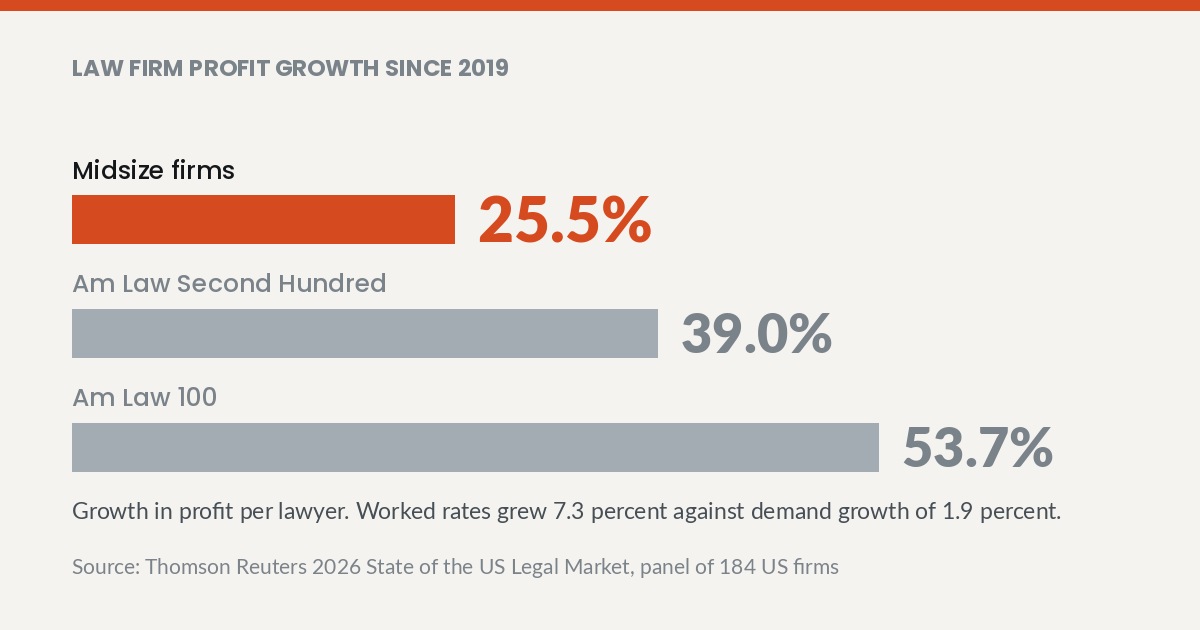
Law firm profit growth since 2019: Midsize firms 25.5%, Am Law Second Hundred 39.0%, Am Law 100 53.7%. Thomson Reuters 2026 State of the US Legal Market, panel of 184 US firms

A law firm consultant reading the 2026 Thomson Reuters State of the US Legal Market will find one number that matters. Profit per lawyer since 2019 grew 25.5 percent at midsize firms and 53.7 percent at Am Law 100 firms. Both cohorts grew, and the distance between them is compounding.

The gap, not the growth, is the finding

Most coverage of legal market data reports the top of the market. The 2026 Thomson Reuters State of the US Legal Market gives all three cohorts. Profit per lawyer since 2019 grew 25.5 percent at midsize firms, 39.0 percent at Am Law Second Hundred firms and 53.7 percent at Am Law 100 firms.

The panel behind those figures covered 184 US firms, comprising 50 Am Law 100 firms, 58 Second Hundred firms and 76 midsize firms. The cohorts are not small samples of outliers. They describe a market-wide pattern with a consistent direction.

Every cohort grew profit per lawyer, which is the part usually missing from the anxious version of this story. Midsize firms as a group are not failing. They are gaining ground more slowly than the firms they compete with for talent and for work.

A gap in compounding rates does not stay constant. Each year the larger firms convert their profit advantage into higher associate compensation, better laterals and deeper investment. That is how a difference in growth rates becomes a difference in kind.

The profit came from pricing, not from volume

Thomson Reuters reports average law firm profit growth of 13.0 percent year over year for 2025. The composition of that growth is the important part. Worked rate growth ran 7.3 percent against demand growth of 1.9 percent.

Rates rose far faster than the volume of work being performed. That is a pricing result rather than a growth result. Firms did not win materially more work, they charged materially more for the work they already had.

Pricing is a legitimate lever and firms were right to use it. The problem is that it is finite in a way volume is not. A firm can raise rates until clients push back, and client tolerance is the ceiling.

Demand growth of 1.9 percent tells a midsize firm something specific about strategy. Matter volume is not expanding fast enough to carry a profit plan on its own. Any firm budgeting for both rate increases and demand recovery is counting the same lever twice.

Realization is where the rate increase leaks

A worked rate is not a collected rate. Thomson Reuters puts collection realization against worked rates at 90.3 percent for 2025. The difference between the rate a firm sets and the rate it collects is a management problem rather than a market condition.

The leak is not evenly distributed across the firm. Associate realization sits at 85.6 percent, the lowest of any timekeeper level in the Thomson Reuters data. That is the cohort a firm depends on for margin.

Associate write-downs happen for identifiable and fixable reasons. Work assigned above a lawyer's capability, matters staffed without a budget and time entered without a usable narrative all produce the same result. Each is a billing hygiene issue a firm can fix without asking a client for anything.

Recovering realization points is quieter than raising rates and easier to defend. A rate increase requires a client conversation every single year. A realization improvement requires an internal process change once.

The expense side is moving faster than the rate

Rate growth does not reach the bottom line intact. Thomson Reuters reports direct expenses, meaning fee-earner compensation and benefits, consuming 32 percent of the average firm's revenue. Direct spend on lawyer compensation rose 8.2 percent while overhead per lawyer rose 4.3 percent and support staff cost rose more than 6 percent.

Lawyer compensation rising faster than worked rates is the structural squeeze. The talent market sets compensation and the client market sets rates, and the two are never negotiated with each other. A firm caught between them absorbs the difference in margin.

Headcount growth adds another layer to that pressure. Thomson Reuters reports lawyer headcount up 2.9 percent across the panel. Total headcount since January 2023 rose 8.2 percent at midsize firms, 9.4 percent at Second Hundred firms and 5.1 percent at Am Law 100 firms.

Midsize firms grew headcount faster than the largest firms while growing profit per lawyer more slowly. Adding people without adding proportional profit is the definition of a dilutive expansion. The question a midsize firm should ask is whether new headcount bills at a realization the firm can live with.

How the gap transmits into the talent market

Profit per lawyer is not an abstract scoreboard. It determines what a firm can pay an associate class and what it can offer a lateral partner without diluting existing partners. A firm growing profit per lawyer faster than its competitors sets the compensation benchmark everyone else has to answer.

Thomson Reuters put direct spend on lawyer compensation up 8.2 percent for 2025. Firms in every cohort paid that increase, but they did not all fund it from the same profit base. The firm with slower profit growth funds the same compensation increase out of a thinner margin.

That is the transmission mechanism between the two cohorts. Compensation is set close to market regardless of a firm's own economics, because the alternative is losing people. A midsize firm therefore imports the cost structure of the Am Law 100 without importing its rate structure.

Recognizing that changes what a midsize firm should optimize. Matching the largest firms on compensation while trailing them on rate requires better realization, better staffing design or a different practice mix. Firms that pick none of the three run a narrower margin every year.

Market structure is shifting underneath the numbers

The available talent pool has started expanding again. The ABA National Lawyer Population Survey for 2025 records total licensed US lawyers at 1,374,720, up 1.38 percent from 1,355,963. That was the first significant rise since 2020.

An expanding lawyer population changes the recruiting calculus as well. A pool that grows again loosens a market that had been tightening for several years running. Firms that built their retention assumptions during the scarcity period should test those assumptions against current conditions.

The market those lawyers work in remains fragmented. US Census County Business Patterns for 2023 counted 165,491 offices of lawyers establishments with an average of 6.61 employees. A market of very small firms is a market where consolidation has room to run.

Consolidation is concentrated at the small end of the market. Fairfax Associates reports 76 percent of law firm mergers in 2025 involved a firm of five to twenty lawyers, up from 69 percent in each of the prior two years. That was across 59 completed mergers in the year. Small firms are being absorbed while midsize firms compete for the same laterals as the largest ones.

What a midsize firm can act on

The gap is not closable through rate alone. Am Law 100 firms raise rates from a stronger client position and a different matter mix. A midsize firm chasing that pricing curve without the matter mix behind it loses clients rather than gaining margin.

Matter profitability before matter volume

Most midsize firms measure revenue by practice and profit by firm. The gap between those two views hides matters that generate revenue and destroy margin. Profitability at matter level, including write-downs and write-offs, changes which work a firm chases next year.

Billing hygiene as a margin program

Collection realization at 90.3 percent and associate realization at 85.6 percent describe recoverable money. Narrative quality, timely entry and budget discipline move those numbers without a rate conversation. Firms that treat billing hygiene as an administrative chore leave the easiest margin on the table.

Timekeeper mix and staffing design

Work assigned above its appropriate level is the most common cause of associate write-downs. Staffing matters deliberately, with the right timekeeper level on each task, protects both realization and client relationships. Alternative fee arrangements only work when a firm knows what a matter costs to deliver.

None of this is a strategy problem in the conventional sense. It is operating discipline applied to a business that historically managed itself through rate increases. Firms that want that discipline installed without adding a permanent executive line often start with a fractional COO engagement and a defined operating agenda.

The 2026 Thomson Reuters data does not describe a midsize crisis. Midsize firms grew profit per lawyer 25.5 percent since 2019, which is a good outcome in most industries. The problem is that they grew it in a market where their direct competitors grew 53.7 percent.

Compounding gaps do not announce themselves in a single year. They show up as a lateral who takes a different offer, a client who moves a matter and an associate class that costs more than the last one. The firms that close the gap will do it on the expense and realization side, because the rate side is already spent.

Frequently Asked Questions

Should my firm raise rates again next year?
Rate increases remain available but produce less than they used to. Thomson Reuters reported worked rate growth of 7.3 percent against demand growth of 1.9 percent for 2025, which means the market has already been pricing aggressively. A firm raising rates without improving realization is increasing the number it writes down. The sequence that works is realization first and rate second.

What does profit per lawyer actually tell a firm?
It measures how much profit the firm generates for each lawyer it employs, combining pricing, realization, expense control and staffing design. Thomson Reuters recorded growth since 2019 of 25.5 percent at midsize firms against 53.7 percent at Am Law 100 firms. The measure is useful because it normalizes for firm size. It becomes misleading when read without the headcount trend beside it.

How do I know whether my realization problem is fixable?
Realization losses fall into two categories, client resistance and internal process failure. Write-downs traced to unclear narratives, late time entry or work staffed above its level are internal and correctable. Thomson Reuters reports associate realization at 85.6 percent, the lowest of any timekeeper level, which points toward staffing and supervision rather than client pushback. A firm that categorizes write-downs by cause for one quarter will know which problem it has.

Is merging the right answer for a small or midsize firm?
Merger activity is concentrated among smaller firms right now. Fairfax Associates reported 76 percent of law firm mergers in 2025 involved a firm of five to twenty lawyers, up from 69 percent in each of the prior two years. A merger solves scale and coverage problems but does not solve realization or expense discipline. Firms carrying operating problems into a merger usually carry them out the other side.

Why is lawyer compensation growing faster than rates?
The two prices are set in entirely different markets. Thomson Reuters reported direct spend on lawyer compensation up 8.2 percent while overhead per lawyer rose 4.3 percent. Talent competition sets compensation and client tolerance sets rates, with no mechanism connecting the two. Firms absorb the difference until they change either their staffing design or their matter mix.

Where should a managing partner start if none of this is measured?
The first step is a matter-level profitability view covering a full year of closed work. That view identifies which practices and which clients fund the firm and which ones consume it. The second step is a write-down analysis by cause, which converts a realization percentage into a list of fixable behaviors. Both take weeks rather than months and require no client conversation at all.

Thursday, January 8, 2026

Understanding Business Strategy: Cost Leadership vs. Differentiation


Introduction: The Two Fundamental Paths to Winning in Business

Every successful business needs a clear plan to compete and win in its market. While there are countless tactics, most winning strategies boil down to one of two fundamental approaches. This guide will explain the core strategies of Cost Leadership and Differentiation, using concepts from Michael Porter’s renowned generic strategy framework. Understanding this fundamental choice is the first step to understanding how the world's most successful companies operate.

1. The First Path: Competing on Price (Cost Leadership)

The Cost Leadership strategy focuses on becoming the most efficient business in an industry, offering products or services at highly competitive prices.

How They Do It:

  • Operational Efficiency: Streamlining every process to reduce waste, time, and expense, ensuring the business runs like a well-oiled machine.
  • Economies of Scale: Producing goods in large volumes, which lowers the cost per item and allows the company to pass those savings on to the customer.
  • Tight Cost Control: Diligently managing all expenses, from raw materials to marketing, to maintain the lowest possible cost structure.

Who Does This Well?

  • Walmart dominates retail by leveraging its massive scale and hyper-efficient supply chain to offer "everyday low prices."
  • McDonald's: Employs standardized, highly efficient processes in its kitchens worldwide to deliver fast, affordable food.
  • Ryanair: Masters tight cost control in every aspect of its airline, from aircraft purchasing to no-frills service, to offer some of the cheapest flights in Europe.

Now that we see how companies win by being the most affordable, let's look at how others win by being the most unique.

2. The Second Path: Competing on Uniqueness (Differentiation)

The Differentiation strategy focuses on creating a unique product, service, or brand identity that customers perceive as superior, enabling the company to charge higher prices.

How They Do It:

  • Uniqueness: Developing distinct features, designs, or capabilities that competitors cannot easily replicate.
  • Superior Quality: Using premium materials, craftsmanship, and service to deliver a product that is demonstrably better than alternatives.
  • Innovation: Constantly pushing the boundaries with new technology, features, and ideas that captivate the market.
  • Strong Branding: Building a powerful brand image and story that creates an emotional connection with customers, making them loyal advocates.

Who Does This Well?

  • Apple: Excels through innovative product design, superior quality, and a powerful brand that commands a premium price and fierce customer loyalty.
  • BMW: Differentiates itself as the "Ultimate Driving Machine" through superior engineering, high-quality materials, and a brand synonymous with performance luxury.
  • Starbucks: Sells more than coffee by creating a unique customer experience, a strong brand identity, and a sense of community that justifies its premium prices.

With both strategies defined, the difference becomes clearer when they are seen side by side.

3. At a Glance: Cost Leadership vs. Differentiation

Attribute

Cost Leadership Strategy

Differentiation Strategy

Primary Goal

Become the lowest-cost producer.

Create a unique product/service.

Core Focus

Efficiency and affordability.

Creativity and emotional connection.

Pricing Power

Offers competitive, low prices.

Commands premium pricing.

Key Examples

Walmart, McDonald's, Ryanair

Apple, BMW, Starbucks

This comparison highlights a critical point: a company must choose its path deliberately.

4. The "So What?": Why a Clear Choice is Crucial for Success

This strategic choice is not a minor decision; it is a fundamental commitment that dictates how resources are allocated, how value is communicated, and how a brand positions itself in the marketplace. Organizations that clearly define their chosen path gain significant advantages, while those attempting to be both the cheapest and most unique often fail.

  1. Build a Stronger Market Identity: A clear strategy helps customers understand what a brand stands for. Whether it's the best price or the best quality, this clarity makes a company memorable and distinct.
  2. Enhance Customer Trust: When a company consistently delivers on its promise—whether that's affordability or premium quality—it builds deep and lasting trust with its customers.
  3. Achieve Consistent Growth: A focused strategy allows a company to allocate its resources (time, money, and talent) more effectively, driving consistent and sustainable growth.

Clarity of focus, supported by execution excellence, remains the key to enduring success.

5. Final Takeaway

Cost Leadership and Differentiation are two distinct and powerful ways for a business to achieve a competitive advantage. The first wins by being the most efficient and affordable, while the second wins by being the most creative and unique. The most successful and enduring companies are those that choose one of these paths, commit to it fully, and execute their strategy better than anyone else. To read more visit Competitive Strategy Consulting

Wednesday, January 7, 2026

Gaining Your Competitive Edge: An Introduction to Three Core Business Strategies


Introduction: What is a Competitive Edge and Why Does it Matter?

Ever wonder how some companies thrive by offering the lowest prices, while others persuade customers to pay a premium for nearly the same product? The answer isn't luck—it's strategy. In any competitive marketplace, businesses use carefully planned strategies to gain a competitive edge, an advantage that sets them apart from rivals. This edge is essential for achieving long-term profitability and ensuring the business can grow sustainably.

This overview introduces three core strategies that represent unique pathways to success: Cost Leadership, Differentiation, and Focus. Understanding how each one works is the first step in learning how businesses align their goals with what customers truly want.

1. The Cost Leadership Strategy: Competing on Price

The path of Cost Leadership is one where a company leverages operational efficiency to deliver products or services at the lowest cost, making its primary goal straightforward: to become the undisputed lowest-cost producer in its industry. The entire business is engineered for frugality. By relentlessly optimizing every step from sourcing raw materials to final distribution, the company creates a cost structure that its competitors simply cannot match, giving it the power to win over price-driven customers.

  • Core Concept:
    • Goal: To deliver products or services at the lowest possible cost.
    • Method: Mastering operational efficiency.

While competing on price is a powerful approach, another way to win is by offering something completely different.

2. The Differentiation Strategy: Competing on Uniqueness

This path emphasizes creating unique value through innovation, branding, or superior quality to make a product or service stand out from the competition. Instead of focusing on being the cheapest, this strategy is about being the best in a way that customers are willing to pay more for. To achieve this, a differentiator intentionally invests in areas that create tangible value for the customer—perhaps by sourcing superior materials, funding groundbreaking R&D for innovative features, or building an unforgettable brand identity that others can't easily replicate.

  • Core Concept:
    • Goal: To create a unique and superior value proposition.
    • Method: Using innovation, branding, or quality.

While differentiation aims for broad appeal based on uniqueness, the Focus strategy narrows the field to specialize even further.

3. The Focus Strategy: Competing in a Niche

The Focus strategy involves narrowing attention to niche markets to deliver tailored solutions to specialized audiences. This strategy requires intense discipline. By deliberately ignoring the broader market and concentrating all its energy on a specific group's unique needs, a business can achieve a level of expertise and customer intimacy that larger, more generalized competitors cannot replicate. It wins by becoming the go-to expert for that specialized audience.

  • Core Concept:
    • Goal: To dominate a specific market segment or niche.
    • Method: Delivering tailored solutions for a specialized audience.

Each of these paths—price, uniqueness, and specialization—offers a powerful blueprint for success. Let's compare them directly to see how their core mechanics differ.

4. Comparing the Strategies at a Glance

Strategy

Primary Goal

How It Works

Cost Leadership

Lead on pricing

Through operational efficiency

Differentiation

Stand out through uniqueness

Through innovation, branding, or superior quality

Focus

Dominate a niche

By delivering tailored solutions to a specialized audience

5. Conclusion: Choosing Your Path

The core lesson is that understanding these three distinct strategies empowers a business to make smart, deliberate decisions and maximize its competitive potential. Whether an organization aims to lead on price, stand out through uniqueness, or dominate a niche, a clear strategic path is vital.

Ultimately, any of these strategies can lead to outstanding success. The right choice always depends on a business's specific goals, its unique strengths, and the demands of the market it serves. Visit competitive strategy consultant to learn more. 

Wednesday, November 5, 2025

Exit Strategy Planning: A Long-Term Guide to Maximizing Your Business Value


Most business owners mistakenly believe exit planning begins only when they're ready to sell. The reality is that businesses with well-executed exit strategies achieve 20-40% higher valuations than those sold hastily. This significant premium results from years of strategic preparation that builds enterprise value systematically.

Successful exit planning involves three critical pillars: valuation optimization, documentation preparation, and strategic timing. Businesses with structured exit roadmaps typically command premium valuations compared to reactive sales because they've methodically addressed buyer concerns and maximized their market appeal.

The most valuable business transitions result from owners who understand that exit strategy planning is an ongoing process, not a last-minute scramble. This comprehensive guide provides SMB owners with a practical roadmap to build value systematically while preparing for their eventual transition.

Understanding Exit Strategy Planning: More Than Just Finding a Buyer

Exit strategy planning is a systematic approach to building and preserving business value while preparing for ownership transfer. This differs fundamentally from simply "selling a business" because true exit planning integrates operational improvements, financial optimization, and succession preparation over multiple years.

Many owners incorrectly assume exit planning begins 1-2 years before sale. Successful strategies actually require 3-5 years of preparation to maximize value and maintain flexibility across different exit options. This extended timeframe allows for meaningful improvements that buyers value and pay premiums to acquire.

SMB owners have several exit options available:

  • Strategic sales to competitors seeking market expansion
  • Financial buyer acquisitions through private equity or investment groups
  • Management buyouts, where existing leadership purchases the business
  • Family succession transfers to next-generation family members
  • Employee stock ownership plans (ESOPs) that transfer ownership to employees

Each option requires different preparation strategies and documentation. Early planning keeps all options viable while building the flexibility to choose the most advantageous path when market conditions align favorably.

The foundation of any successful exit strategy lies in systematically building enterprise value that attracts premium buyers and supports higher multiples.

The Value-Building Foundation: Optimizing Your Business for Maximum Sale Price

Creating Predictable Revenue Streams

Securing long-term customer contracts transforms business valuation by providing predictable cash flows that buyers value highly. Converting month-to-month relationships into annual or multi-year agreements demonstrates revenue stability and reduces buyer risk perceptions.

Specific strategies for revenue predictability include implementing subscription models where applicable, developing service contracts that extend beyond initial product sales, and creating maintenance agreements that generate recurring income. These approaches provide the cash flow consistency that supports higher valuation multiples.

Documenting customer relationships through formal agreements, purchase order systems, and relationship mapping demonstrates stability to potential buyers. Diversifying the customer base reduces concentration risk - a major concern for acquirers who see over-dependence on key accounts as a valuation detractor.

Building Competitive Differentiation

Enhancing product and service differentiation creates defensible market positions that justify premium valuations. Developing intellectual property, proprietary processes, exclusive supplier relationships, and specialized expertise prevents competitors from easily replicating business advantages.

Documentation strategies for competitive advantages include patent filings, trademark protection, and comprehensive process documentation that clearly articulates the business's unique market position. Businesses with clear differentiation command higher multiples in acquisition scenarios because buyers pay premiums for sustainable competitive advantages.

Operational Excellence and Scalability

Streamlining operations for scalability and efficiency prepares businesses for new ownership while reducing buyer integration risks. Systems documentation, process standardization, and technology implementations allow businesses to operate effectively without heavy owner involvement.

Management team development and succession planning for key roles create organizational structures that function independently. Operational independence directly correlates with higher valuations since buyers pay premiums for businesses that don't require their constant oversight or management intervention.

Professional valuation provides the baseline for measuring value-building progress and identifying improvement opportunities.

Professional Valuation: Establishing Your Baseline and Tracking Progress

Working with M&A Advisors and Certified Valuation Analysts

Engaging professional help early in the exit planning process, not just when ready to sell, provides objective assessments using multiple methodologies. M&A advisors and certified valuation analysts employ discounted cash flow analysis, comparable company analysis, and precedent transaction analysis to determine accurate market values.

The cost-benefit analysis of professional valuation services typically shows positive returns because the insights gained result in value improvements that exceed advisory costs. Selecting qualified advisors requires evaluating relevant industry experience and proven track records in SMB transactions similar to the business being valued.

Understanding Valuation Methodologies

Three primary valuation approaches provide comprehensive business assessments. Discounted cash flow analysis focuses on future earnings potential by projecting cash flows and discounting them to present value. Comparable company analysis benchmarks against similar businesses currently operating in the market. Precedent transaction analysis examines the actual sale prices of comparable companies recently sold.

Buyers typically use multiple approaches and weigh them based on business characteristics. This makes it important to strengthen all value drivers rather than focusing on a single metric. Understanding these methodologies helps owners make informed decisions about value-building investments and realistic expectations about multiples for different business types and sizes.

Creating Value Improvement Action Plans

Professional valuations identify specific improvement opportunities and provide roadmaps for value enhancement. Systematic approaches to addressing valuation gaps include prioritizing high-impact improvements and measuring progress over time through regular reassessments.

Frameworks for setting value improvement targets should include timeline planning for implementation and milestone tracking toward exit goals. Regular progress measurement ensures value-building efforts produce measurable results that translate into higher valuations when sale opportunities arise.

Building value requires proper documentation to support claims and facilitate due diligence when the time comes to sell.

Documentation Requirements: Building the Paper Trail for Success

Essential Legal Framework Documents

Comprehensive documentation packages for business sales start with foundational corporate governance documents. Articles of Incorporation, shareholder agreements, and board resolutions establish a legitimate business structure and ownership clarity that buyers require before proceeding with acquisitions.

Maintaining current and accurate records includes annual filings, tax returns, and compliance documentation. Organizing these materials for easy access during due diligence processes expedites transactions and demonstrates professional business management to potential buyers.

Transaction-Specific Documentation

Key transaction documents include Letters of Intent (LOI), Non-Disclosure Agreements (NDA), Asset Purchase Agreements, Stock Purchase Agreements, and detailed Disclosure Schedules. Understanding each document's purpose and preparing properly expedites negotiations and reduces legal complications.

Employment and Transition Agreements for situations where owners or key employees remain post-sale require careful structuring. These agreements should define compensation structures, role definitions, and performance expectations that create value rather than complications for new ownership.

Financial and Operational Documentation

Financial documentation buyers expect includes audited financial statements, tax returns, management reports, and cash flow projections. Quality of earnings analysis requires clean financial records that support higher valuations by reducing buyer uncertainty about actual business performance.

Operational documentation encompasses customer contracts, supplier agreements, employment records, and intellectual property registrations. Comprehensive documentation reduces buyer risk perceptions and supports asking prices by providing evidence of business stability and growth potential.

Building Buyer Trust Through Documentation Excellence

Thorough documentation builds buyer confidence, reduces legal risks, and expedites negotiation processes. Common documentation gaps create delays or reduce valuations by increasing buyer concerns about hidden liabilities or operational problems.

Systematic approaches to maintaining transaction-ready records include regular documentation audits, professional record-keeping systems, and proactive legal compliance. Businesses with excellent documentation typically close faster and at higher valuations than those requiring extensive document preparation during sales processes.

Strategic timing considerations ensure even perfectly prepared businesses achieve maximum value.

Strategic Timing: Reading Market Conditions and Personal Readiness

Market Condition Assessment

Economic cycles, industry trends, and buyer market conditions significantly impact business valuations and transaction success rates. Leading indicators of favorable selling conditions include low interest rates, high buyer activity, and strong market multiples that support premium valuations.

Industry-specific timing considerations include regulatory changes, technological disruptions, and competitive dynamics that might accelerate or delay optimal sale timing. Monitoring these conditions and adjusting exit timelines accordingly helps maximize value when market conditions align favorably.

Business Performance Timing

Selling from positions of strength requires consistent financial performance and positive growth trends. Buyers value businesses showing upward trajectory versus those with declining or volatile performance because growth patterns suggest continued success under new ownership.

Seasonal considerations and multi-year performance patterns impact buyer perceptions and valuations. Forward-looking projections that support continued growth under new ownership help businesses sold during peak performance periods achieve higher multiples than those with uncertain futures.

Personal and Family Readiness

Personal readiness factors include financial preparedness for post-sale life, emotional readiness for ownership transition, and family considerations that impact timing decisions. Clear post-sale plans whether retirement, new business ventures, or other pursuits, impact negotiation confidence and decision-making during the sale process.

Having defined objectives for life after business ownership helps owners make better decisions about timing, pricing, and deal structure during negotiations with potential buyers.

External Factor Considerations

External factors including political stability, tax policy changes, and global economic conditions influence buyer sentiment and market stability. Staying informed about these factors and consulting with advisors helps optimize timing decisions for maximum value capture.

External events can create windows of opportunity or suggest delaying transactions until conditions improve. Understanding these dynamics helps owners time their exits for maximum financial benefit.

Success in exit strategy planning requires integrating all elements into a cohesive, long-term plan.

Creating Your Integrated Exit Roadmap

Developing Your 3-5 Year Plan

Comprehensive exit roadmaps integrate value building, documentation preparation, and market timing considerations into systematic plans. Year-by-year planning approaches build methodically toward exit readiness while maintaining operational excellence and growth momentum.

Milestone setting, progress tracking, and plan adjustment processes maintain momentum while adapting to changing circumstances. Longer planning horizons typically result in higher valuations and more successful transactions because they allow time for meaningful improvements that buyers value.

Building Your Advisory Team

Professional teams required for successful exit planning include M&A advisors, attorneys, accountants, and financial planners. Each professional contributes specialized expertise at different stages of the planning process, from initial valuation through final closing.

Coordination among advisors requires clear communication protocols and decision-making processes that keep exit planning on track while managing costs effectively. Early engagement of key advisors prevents last-minute scrambling and ensures all aspects of the exit plan work together cohesively.

Implementation and Progress Monitoring

Systematic approaches to implementing exit roadmaps include project management techniques, accountability measures, and regular assessment processes. Measuring progress against value-building objectives and adjusting strategies based on results ensures continuous improvement toward exit goals.

Common implementation challenges include maintaining focus over multi-year timelines and balancing exit preparation with daily operations. Solutions include regular milestone reviews, professional accountability, and systematic progress tracking that maintains momentum toward successful exits.

The Kamyar Shah Integrated Exit Strategy Framework

Kamyar Shah Consulting Services provides specialized exit planning support through their comprehensive Four Pillars methodology for businesses preparing for transition. This framework addresses Time, Budget, Agreement, and Support components essential for successful exit execution.

The integrated approach combines fractional COO services during the value-building phase with strategic consulting to optimize operational systems for buyer appeal. Working with businesses 3-5 years before intended sale, the firm focuses on creating repeatable and reliable operational processes that support premium valuations.

Operational Excellence for Exit Readiness

Kamyar Shah's fractional COO services specifically prepare businesses for ownership transition by establishing management systems that operate independently of current ownership. This includes implementing scalable processes, developing management team capabilities, and documenting operational procedures that buyers value.

The firm's operational assessment identifies value-building opportunities while establishing systems for measuring progress toward exit goals. This hands-on approach ensures businesses achieve the operational independence that commands premium multiples from potential buyers.

Strategic Value Enhancement

Through strategic consulting engagements, Kamyar Shah helps business owners identify and implement value-building initiatives across operations, marketing, and strategic positioning. The firm's cross-industry experience provides insights into competitive differentiation strategies that enhance market appeal to buyers.

The consulting approach includes market positioning analysis, operational efficiency improvements, and leadership development programs designed to create sustainable competitive advantages. These improvements directly contribute to higher valuations when businesses enter the market.

Kamyar Shah Consulting Services backs their exit planning methodology with a 100% satisfaction guarantee, ensuring business owners receive measurable value-building results throughout their preparation process. This commitment reflects their confidence in delivering repeatable improvements that translate into successful business transitions.

Your Path to a Successful Business Transition

Successful business exits result from strategic preparation, not lucky timing or market conditions alone. The three key pillars of systematic value building, comprehensive documentation, and strategic timing work together to create maximum value and transaction success.

Effective exit planning integrates all elements to reinforce each other. Operational excellence supports higher valuations, comprehensive documentation expedites transactions, and strategic timing maximizes market opportunities. This integrated approach produces the significant valuation premiums achieved through proper preparation versus reactive approaches.

SMB owners ready to begin their exit planning journey should start with baseline valuations, assemble advisory teams, and develop comprehensive roadmaps aligned with personal and business objectives. The best exits start with immediate preparation, regardless of intended sale timeline.

Successful business transitions are achievable when approached systematically, supported by professional advice, and executed with patience and persistence over appropriate time horizons. Begin your exit planning assessment today - your future self will appreciate the preparation.

Frequently Asked Questions

Q: How early should I start exit planning for my business? A: Start exit planning 3-5 years before your intended sale date. This timeframe allows for meaningful value improvements and proper documentation while maintaining flexibility across different exit options.

Q: What's the most important factor in maximizing business value? A: Creating predictable revenue streams through long-term contracts and recurring customers provides the foundation for premium valuations because buyers value cash flow stability and reduced risk.

Q: Do I need professional help for exit planning? A: Yes, engaging M&A advisors and certified valuation analysts early provides objective assessments and improvement strategies that typically result in value increases far exceeding advisory costs.

Q: How do I know if it's the right time to sell my business? A: Optimal timing combines strong business performance, favorable market conditions, and personal readiness. Selling from positions of strength during peak performance typically achieves higher valuations.

Q: What documentation do I need to prepare for selling my business? A: Essential documentation includes corporate governance documents, financial statements, customer contracts, employee agreements, and intellectual property registrations. Comprehensive documentation builds buyer confidence and supports higher valuations.

Cyber, Data Privacy, and Security | VWCG OS

Module 12 serves as the security and compliance layer within the VWCG OS framework. Instead of isolating cybersecurity and data privacy as ...